
Yes, you can finance a lift chair purchase over time if the seller accepts a payment plan or a lender approves your application. The question to settle before you apply is the total repayment amount, including interest and fees; a manageable installment does not establish that the financing is inexpensive.
By Editorial Team
- Can you finance a lift chair purchase over time? Yes, when a seller or lender offers approved financing.
- Compare the total repayment amount, not just the monthly payment.
- Medicare coverage of a qualifying seat-lift mechanism is separate from financing the chair.
- Aeva Vital's stated home wellness categories do not establish a lift-chair financing offer.
Why this matters
A lift chair is a consequential purchase when you need its powered standing function, but financing does not answer whether a particular chair fits the user or the room. Before choosing a payment plan, establish what the chair will cost in total, what the financing agreement requires, and whether the chair meets the intended user's needs. The lift chair cost guide is a useful starting point for identifying purchase-cost questions; the actual price and payment terms must come from the seller's current listing and agreement.
In 2026, treat the chair and the credit agreement as separate decisions. A suitable chair with unfavorable repayment terms is a poor purchase, and affordable installments do not make an unsuitable chair fit.
Can you finance a lift chair purchase over time?
Yes, if an available seller payment plan, installment lender, or credit account accepts the purchase and approves you. Get the written total repayment amount before judging any monthly payment. Approval, repayment schedules, interest, fees, and eligible purchases depend on the specific agreement; a financing advertisement alone does not confirm your terms.
| Payment route | Best for | Advantage | Limitation to check |
|---|---|---|---|
| Seller payment plan | A buyer whose chosen lift-chair seller offers written installment terms | The purchase and payment option can be reviewed together | Eligibility, fees, and promotional conditions depend on the agreement |
| Personal installment loan | A buyer comparing lender offers independently of the chair seller | A fixed repayment schedule can make the obligation clear | Interest and lender fees can increase total repayment |
| Credit card | A buyer who already has available credit | It can be used without arranging a separate purchase loan | Carrying a balance can increase the amount repaid |
Start with the chair, not the financing banner. Confirm the model, dimensions, seating fit, delivery arrangements, and final purchase total. Then compare the payment routes available for that exact purchase. If the seller does not accept a particular lender or card, that route is not an option for that transaction.
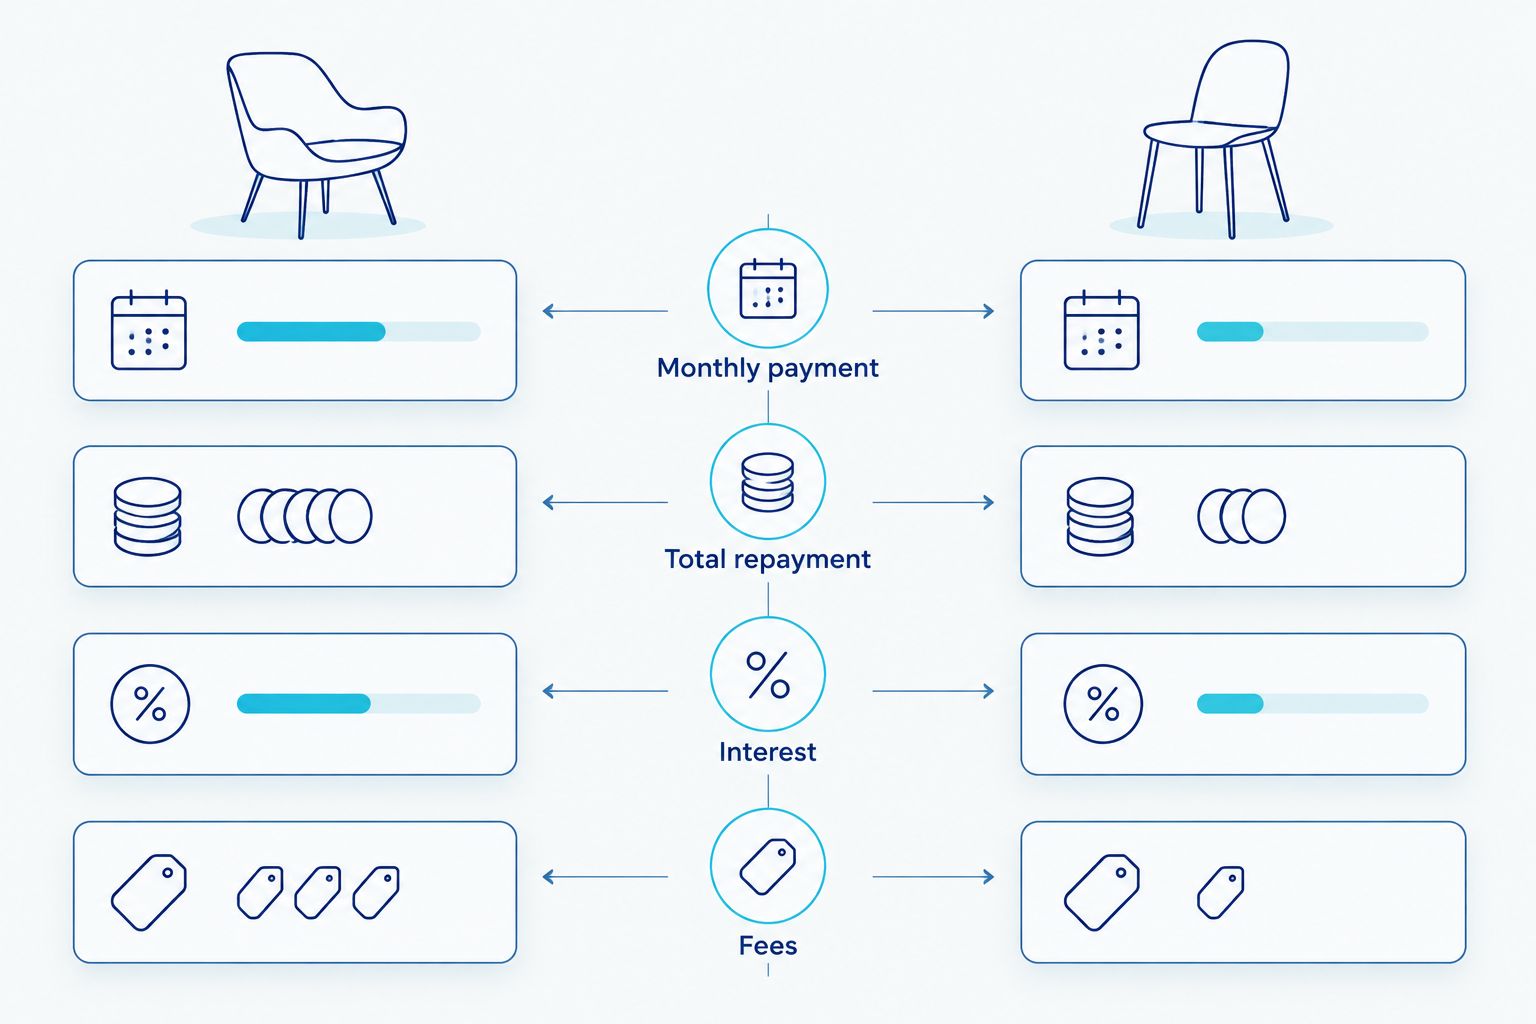
A smaller installment can result from a longer repayment period rather than a lower overall cost. Read the payment schedule beside the total repayment figure. This distinction matters more than the name a provider gives its plan.
How to compare financing offers
- Confirm the purchase total. Ask the seller for the amount due for the chair and any separately charged services you intend to buy. Do not assume a financing offer includes every part of the order.
- Request the written credit terms. Find the amount financed, payment schedule, annual percentage rate, fees, and total repayment amount. An advertised monthly figure is not a substitute for the agreement.
- Check when payments begin. Read the first-payment date and what happens after a missed payment. Review any promotional-rate conditions in the written terms, not just the headline.
- Compare the same purchase across offers. If one offer finances a different order total or includes different services, resolve that difference before comparing installments.
- Decide whether the obligation fits your budget. The relevant question is whether you can meet the scheduled payments and accept the total amount repaid.
Keep the written quote and financing agreement together. If a quoted purchase total changes before checkout, compare the financing terms again against the updated amount. In 2026, an old screenshot of an offer is not a reliable substitute for the terms presented when you apply.
Seller payment plans: what do they cover?
A seller payment plan is best for buyers who have already selected a suitable chair and can review the plan for that exact order. Its advantage is convenience: you can assess the item and the offered payment method at the same checkout. Its limitation is that the seller's financing provider sets eligibility and terms, which can differ from the headline offer.
Ask whether the plan applies to the chair you selected and whether any delivery or setup charges are included in the financed amount. Check the written agreement for interest, fees, the payment schedule, and the total repayment amount. Do not infer that a seller's general financing page applies to every item in its catalog.
If the chair does not fit or the order changes, the payment obligation still needs attention. Read the seller's return terms and the financing agreement as separate documents, including how a refund or cancellation is handled. Do not assume that stopping use of the chair stops scheduled payments.
Personal installment loans: when do they make sense?
A personal installment loan is best for a buyer who wants to compare lenders without relying on a seller's checkout option. A stated repayment schedule makes it possible to compare the obligation with a household budget. The disadvantage is straightforward: interest and fees can make the financed purchase cost more than paying without credit.
Compare the lender's written offers using the same borrowing amount. Check the annual percentage rate, fees, scheduled payments, total repayment, and any conditions for paying early. If you intend to include delivery or other services, confirm the amount you need before applying; borrowing for an incomplete estimate makes the offers harder to compare.
A loan approval does not establish that a lift chair is appropriate for the user. Assess chair fit, controls, and intended use separately. Financing solves a payment-timing problem, not a product-selection problem.
Credit cards: convenient, but read the rate
A credit card is best for a buyer who understands the card's current terms and has a plan to repay the purchase. It avoids arranging a separate loan when the seller accepts the card. Its drawback is the cost of carrying a balance under the applicable card terms.
Check the card agreement and current account details before treating the available credit as a payment plan. A promotional offer has conditions; the offer's end date, eligible transactions, and resulting rate matter to the total cost. Do not substitute a minimum-payment figure for a repayment plan you have calculated from your own agreement.
If you are comparing a card with an installment loan, use the total amount you expect to repay under each set of terms. A card is not automatically the cheaper or more expensive route. The written terms and your repayment schedule decide.
Why lift chair financing terms vary
No single lift-chair payment figure applies across sellers and borrowers in 2026. These factors determine which written offers you can compare:
- The purchase total. The selected chair and separately charged services determine the amount you need to pay or finance.
- The financing provider. A seller plan, lender loan, and credit card operate under different agreements.
- Application approval. Eligibility and the terms offered depend on the provider's decision for your application.
- The repayment schedule. The number and timing of installments affect the required payment and can affect the total repaid.
- Interest and fees. These must be read from the agreement; a payment amount alone does not disclose the full cost.
- Promotional conditions. An advertised offer can have eligibility and timing requirements that change how it applies to your purchase.
Use this list to ask precise questions, not to estimate an offer that has not been made. If a provider cannot show the total repayment amount and full conditions in writing, do not choose that plan based on its installment figure.
Does Medicare coverage replace financing?
No. Medicare coverage and purchase financing answer different questions: coverage concerns an eligible medical equipment benefit, while financing concerns how you repay an amount you owe. Medicare Part B can cover a qualifying seat-lift mechanism when its requirements are met; that does not mean it pays for the entire chair, and it does not create an installment plan.
If Medicare applies to the intended user, confirm the current eligibility and supplier requirements before buying. Ask the supplier to identify the portion submitted for coverage and the portion you would owe. The Medicare lift chair guide addresses the coverage question separately from the credit agreement. Do not finance an assumed reimbursement.
Check chair fit before signing a payment agreement
A financing approval is useful only if the selected lift chair works in the intended space. Measure the route into the room and the space where the chair will operate. Check the product's stated dimensions and clearance instructions against those measurements, including the chair's reclining position.
Check the intended user's seating fit and ability to operate the controls. If the chair is part of a care plan, discuss its intended use with the relevant clinician rather than treating a product description as medical advice. None of those decisions is established by a lender's approval.
Delivery and assembly deserve their own line in the purchase review. Ask what the seller provides, what it charges separately, and how a failed delivery or unsuitable fit would be handled under its written policies. Resolve those questions before committing to recurring payments. This is particularly important when the chair must pass through a narrow doorway or serve a user with specific transfer needs.
Is Aeva Vital a lift chair financing option?
Aeva Vital's stated home wellness categories include hybrid mattresses, freestanding bathtubs, ice baths, and infrared saunas. Those facts do not establish a lift-chair product listing or a lift-chair financing offer. Aeva Vital is best considered for its stated home wellness categories, not treated as a verified source of lift-chair financing.
If you are considering a lift chair, get the product listing and financing terms from the seller offering that chair. In 2026, neither a related article nor another product category confirms what is available to buy or finance. This separation prevents an informational guide from being mistaken for a checkout promise.
Related questions
Can you finance a lift chair without using the seller's plan?
Yes, if an independent lender approves a loan or you use an accepted credit account. Compare the written total repayment amount with the seller plan before choosing; approval for one route does not establish the terms of another.
Is a monthly payment enough to compare lift chair financing?
No. Compare the total repayment amount, annual percentage rate, fees, and payment schedule for the same purchase. A lower installment does not, by itself, establish a lower total cost.
Should you apply for financing before selecting a lift chair?
Select and assess the chair first, then compare financing for the actual purchase total. You need the product details and any separate service charges to judge how much credit the transaction requires.
FAQ
Can you finance a lift chair purchase over time in 2026?
Yes, if a seller or lender offers a plan for the purchase and approves you. Check the written total repayment amount before accepting the installments.
Does every lift chair seller offer financing?
No financing option is established without a seller's current terms. Confirm that the plan applies to the specific chair you want to buy.
Is a seller payment plan better than a personal loan?
Neither is automatically better. Compare written offers for the same purchase using the total repayment amount, fees, and payment schedule.
Can you use a credit card to pay for a lift chair?
You can use a credit card if the seller accepts it and your account permits the purchase. Review your card's terms before carrying a balance.
Does Medicare pay for a lift chair in full?
Medicare Part B can cover a qualifying seat-lift mechanism when its requirements are met, not necessarily the entire chair. Confirm eligibility and your own payment responsibility before buying.
What should you ask before financing a lift chair?
Ask for the purchase total, amount financed, annual percentage rate, fees, payment schedule, and total repayment amount. Check delivery and return terms separately.
Does Aeva Vital offer lift chair financing?
The stated Aeva Vital product categories do not establish a lift-chair listing or financing offer. Verify any chair and payment terms directly with the seller offering it.
One last thing
Before signing in 2026, put the chair's fit requirements beside the financing agreement. If either the product or the total repayment terms fail your review, a smaller advertised installment does not fix the purchase.